• -10%
  • New

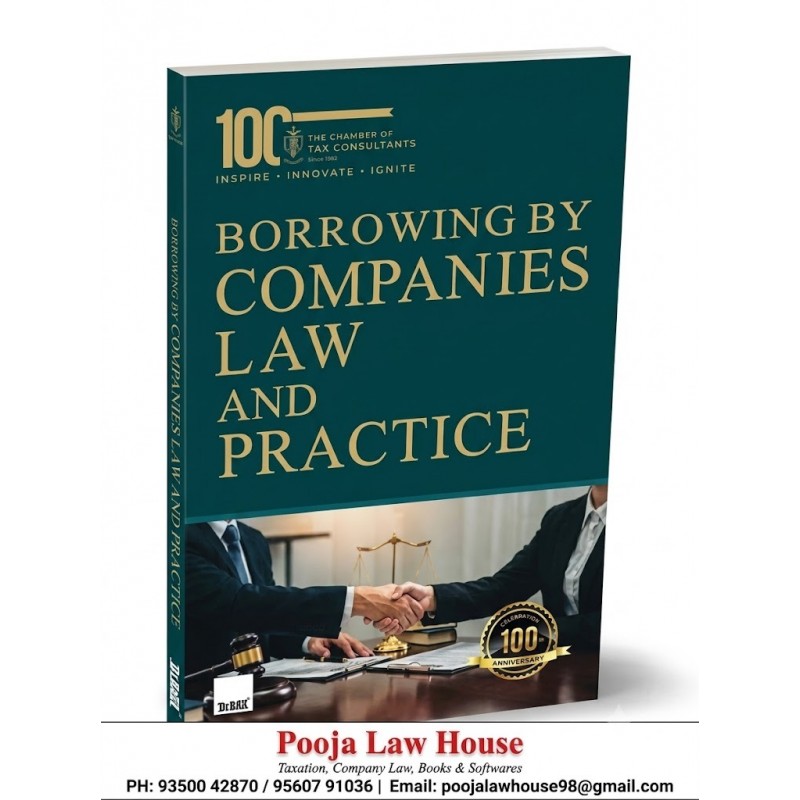
Taxmann Borrowing by Companies Law & Practice by CTC October Edition 2026

₹785.00
₹706.50 Save 10%
Tax excluded
Quantity

Taxmann Borrowing by Companies Law & Practice by CTC October Edition 2026

Borrowing by Companies – Law & Practice is a practical guide to corporate debt in India. It takes the reader from the first Board resolution to the auditor's report. In one volume, it covers:

  • Deposits and loans
  • Convertible notes and debentures
  • Unlisted bonds and Masala Bonds
  • Government schemes for MSMEs
  • Borrowing by listed and unlisted public companies
  • Registration of charges
  • External Commercial Borrowings (ECBs)
  • Audit and tax-audit reporting on loans and borrowings

The book brings law, compliance and audit together. It explains what the law allows, what a company must do and file, and what happens when things go wrong. Start-ups, private companies, MSMEs, unlisted public companies and listed companies each get their own treatment. Readers can go straight to their own situation. It answers the questions practitioners actually face, such as:

  • Must Form DPT-3 be filed when a company holds only exempt deposits?
  • When does share application money turn into a deposit?
  • Must a loss-making company create a Debenture Redemption Reserve?
  • Can a director who joined after an issue be held liable for it?
  • What happens when a charge is not registered in time?
  • What must a company with listed debt securities file, and when?
  • Is a convertible note an ECB?
  • How should an auditor report a term loan used for the wrong purpose?

This book is intended for the following audience:

  • Company Secretaries, for deposit and debenture procedures, charge filings and Board approvals
  • Chartered Accountants and Auditors, for CARO 2020 and Form 3CD reporting on loans and borrowings
  • Corporate Lawyers and In-house Legal Teams, for structuring debt and reading the case law
  • CFOs, Finance and Treasury Teams, for choosing between instruments and planning bond issues and ECBs
  • Directors (including Independent Directors) and Promoters, to understand their personal exposure
  • Start-up Founders, for convertible notes, whom they can borrow from, and the start-up ECB window
  • MSME Owners, for government credit and support schemes and how to apply for them
  • Issuers, Investors and Intermediaries in unlisted bonds and Masala Bonds
  • Students and Young Professionals, as study material backed by case studies and MCQs

The Present Publication is the 2026 Edition. Taxmann publishes it for The Chamber of Tax Consultants (CTC), in the year the Chamber marks its 100th anniversary. The book is the joint work of 16 practitioners: Advocates, Company Secretaries and Chartered Accountants. The noteworthy features of this book are as follows:

  • [Who Can Lend, and on What Terms] A table goes through 16 possible sources of funds, from shareholders, directors and promoters to banks, trusts and overseas lenders. It marks each one as permitted or not, with the conditions or reasons. The deposits chapter lists the receipts that are not treated as deposits, from directors' funds and inter-corporate loans to customer advances
  • [Instruments Compared Side by Side]
    • Deposits, loans, advances, debentures and bonds are compared on nature, source, convertibility, security and duration
    • Convertible notes are compared with CCDs, NCDs, loans and share warrants on eight points. Their definitions under the Companies Act and under FEMA are set out next to each other
    • Other comparisons include listed against unlisted bonds, Masala Bonds against ECBs, and a convertible note against an optionally convertible preference share
  • [Procedures Step by Step] Processes are broken down point by point:
    • The deposit procedure, in 15 numbered points
    • A 13-step route for issuing convertible debentures
    • A five-step roadmap for registering a charge
    • The steps for seeking condonation of delay
    • The ECB chapter runs from internal approvals and loan documentation to the Loan Registration Number and reporting after the loan is drawn. Flowcharts and a summary chart sum up the deposit, debenture and convertible note processes
  • [Forms Linked to the Steps] Steps are linked to the forms that go with them:
    • DPT-1, DPT-2, DPT-3 and GNL-2 for deposits
    • PAS-3, PAS-4, PAS-5, SH-7, MGT-14, and SH-12 for debentures
    • CHG-1 to CHG-9 and INC-28 for charges
    • Form CN, Form ECB 1, Form ECB 2, Form GRN and Form FC-GPR for cross-border transactions
    • Form 3CD for the tax audit
  • [Case Law Explained] The deposits and debentures chapters discuss 15 select rulings. These include the Sahara, Mohan Gupta, Hotel City Plaza and Ind-Swift cases, and rulings on when directors are, and are not, liable for an issue. In all, the book cites more than 30 judgments and orders, from the Supreme Court and High Courts to the NCLT, NCLAT, SAT, SEBI and the House of Lords
  • [Worked Examples and Case Studies] Worked figures show:
    • How a valuation cap and a conversion discount change a convertible note's conversion price
    • How each type of debenture is repaid or converted
    • How a demat deadline is worked out
    • How the guarantee late fee applies to each reporting form
    • The book also has 14 case studies:
      • Three real enforcement matters: Sahara, IL&FS and Tata Motors Finance
      • Four ECB proposals
      • Seven audit scenarios, two of them with MCQs and explained answers
  • [Traps, FAQs and Do's and Don'ts] The book flags the mistakes that cause trouble in practice:
    • Informal loans from friends and family
    • Late DPT-3 filings
    • Share application money held too long
    • Customer advances used as loans
    • Cross-border deals that meet the Companies Act but miss FEMA
    • It also answers 20 FAQs on deposits and debentures. It lists common ECB non-compliances and 12 pairs of do's and don'ts. It works through grey areas in auditing borrowings, such as evergreening and undocumented related-party loans
  • [Ready Reckoners] Ready-to-use tables include:
    • A summary of deposit filings with timelines
    • The timeline and fee table for registering a charge, and a guide to the charge forms
    • Stamp duty rates on debentures
    • Listing criteria and an 18-item compliance calendar for listed non-convertible securities
    • A table of 27 SEBI penalties
    • An 'ECB Parameters at a Glance' table that gives the regulatory source for each point
  • [An Auditor's Toolkit] The audit chapter sets out the auditor’s duties standard by standard. It covers substantive procedures, analytical ratios for testing borrowings, and clause-wise procedures for CARO 2020 and Form 3CD. It also gives:
    • Model wording for clean, qualified and adverse CARO reporting
    • A matrix that maps 14 borrowing situations to the relevant SA, CARO and Form 3CD clauses
    • Six boxed observations from the Quality Review Board on where borrowing audits fall short
  • [Amended & Updated] The ECB chapter reflects the February 2026 overhaul of the ECB framework. It also covers the FEM (Guarantees) Regulations 2026, including the RBI circular of 1st April 2026 on guarantee reporting. Tax references cover both the Income-tax Act 1961 and the Income-tax Act 2025. Form 3CD references also give the corresponding Form 26 under the Income-tax Rules 2026. The unlisted bonds chapter includes market data up to June 2026

The coverage of the book is as follows:

  • Chapter 1 | Debt Financing and Accepting Deposits
    • What debentures, deposits, loans, advances and bonds are, and how they differ
    • Points to weigh before accepting deposits, including deposits from NRIs
    • The full procedure for accepting deposits, from Board approval to repayment
    • Exemptions for private companies and IFSC public companies
    • Equity shares with differential rights as an alternative to debt
  • Chapter 2 | Start Ups
    • Whom a start-up may borrow from, source by source
    • Convertible notes: meaning, eligible investors, agreement terms, advantages, and compliance under the Companies Act and FEMA
    • Borrowing compliances and the Board’s borrowing powers under Sections 179 and 180
    • How Board approval works alongside delegated borrowing powers
    • An adjudication order on a loan taken from a director without Board approval
  • Chapter 3 | Acceptance of Deposits by Private Companies under the Companies Act 2013
    • How deposit regulation developed, and what counts as an exempt deposit
    • Procedure, deposits from members, Form DPT-1 disclosures, and exemptions for private companies and start-ups
    • Valuation, convertibility and premature repayment of deposits
    • The Banning of Unregulated Deposit Schemes Act 2019
    • Penalties, the line between a deposit and a loan, and depositors' remedies before the NCLT
  • Chapter 4 | Debentures
    • Features and types of debentures, with illustrations
    • The procedure for issuing convertible debentures, issue at a discount or premium, and commission
    • Offer letter disclosures, valuation, premature redemption, and whether debentures fall under the Banning of Unregulated Deposit Schemes Act 2019
    • Debenture Redemption Reserve, debenture trustees and the trust deed
    • Demat rules, stamp duty and penalties
  • Chapter 5 | Unlisted Domestic Bonds & Masala Bonds: A Legal and Regulatory Perspective
    • Why unlisted bonds are growing, with recent market data
    • Unlisted bonds: nature, regulatory framework, compliance, features, risks and taxation
    • Masala Bonds: framework, features, how the Companies Act, SEBI and RBI rules apply, and taxation
  • Chapter 6 | SMEs and schemes for SMEs for borrowings
    • The MSME sector and the Union Budget measures to support MSMEs
    • Government schemes such as PMEGP, CGTMSE, PMMY (MUDRA), MSE-CDP, ESDP and the International Cooperation Scheme
    • A summary of other schemes, including PM Vishwakarma, with contact details of MSME offices
  • Chapter 7 | Public Company – Listed and Unlisted: Borrowings
    • How borrowing rules developed, with a year-wise chronology of changes
    • Companies Act provisions on Board powers, deposits, inter-corporate loans and related party borrowings
    • SEBI's LODR, ICDR and NCS Regulations; ECBs, FCCBs and IFSC regulations
    • Listing criteria, the listing process and ongoing compliance for non-convertible securities
    • Penalties and compounding under the Companies Act, SEBI and FEMA
    • Recent developments and the outlook for corporate borrowing
  • Chapter 8 | Registration of charges on the Property/Asset of the Company
    • The company's duty to register a charge, and the lender's right to step in
    • A step-by-step roadmap with filing timelines and fees
    • Modification and satisfaction of charges, the register of charges, and who may inspect it
    • Condonation of delay, Board minutes and penalties
  • Chapter 9 | External Commercial Borrowings (ECB): Overview and applicability for Start-Ups, Private & Public Companies
    • The regulatory set-up and how the ECB regime has evolved
    • Eligible borrowers and lenders, currency, forms, limits, maturity, cost and end-use rules
    • Security, refinancing, conversion into non-debt instruments, parking of proceeds, and reporting
    • Trade Credit, the start-up ECB window and cross-border guarantees
    • Points that differ for public and private companies
    • The process before and after borrowing, the tax interface and compounding
  • Chapter 10 | Auditor’s Duty and Reporting in Respect of Loans and Borrowings
    • How the audit of borrowings, and CARO and Form 3CD reporting, have evolved
    • The auditor's duties under the Standards on Auditing, and substantive procedures
    • Clause-wise reporting under CARO 2020 and Form 3CD
    • The AS and Ind AS framework for borrowings, including Schedule III disclosures
    • Practical difficulties and controversies in auditing borrowings

Each chapter stands on its own and broadly follows this pattern:

  • Chapter Opening — Each chapter opens with its title and the names of its authors. Most then begin with an introduction, synopsis, background or short history. The public company, ECB and audit chapters also trace how the rules changed over time
  • Topic-wise Sections — The law and procedure are then taken up topic by topic, with numbered steps, tables, charts and flowcharts
  • Set Format for Rulings — Most select case laws follow the same headings: background, legal issue, reasoning, and impact and significance
  • Examples and Callouts in Place — Worked examples sit next to the rules they explain. Boxed callouts in the ECB and audit chapters flag key practice points and QRB observations
  • Practical Close — Most chapters close with practical material, such as FAQs, practical challenges, case laws or case studies, do's and don'ts, a filings summary, an at-a-glance table, a penalty table or a contacts directory

About the authors

The Chamber of Tax Consultants

The Chamber of Tax Consultants (CTC) is a Mumbai-based professional body in taxation and allied laws. Founded in 1926 and now in its 101st year, it is guided by the principle ‘Gyanam Param Balam’ (Knowledge is Supreme Strength).


Over the decades, CTC has become a premier national platform for knowledge exchange. It runs Study Circles, Study Groups, conferences, workshops and Residential Refresher Courses (RRCs). Today, it brings together over 4,000 professionals—Advocates, Chartered Accountants, Company Secretaries, Tax Consultants and Students—across fourteen committees.

CTC publishes The Chamber’s Journal (its flagship monthly), The International Tax Journal (quarterly) and Jignyasa (a student publication). Its Student Committee runs essay competitions, debates and moot courts. Its Law and Representation Committee engages with regulators and governments, makes representations on legislative and policy matters and, where necessary, files Public Interest Litigations.

Beyond Mumbai, CTC has branches in Delhi, Pune and Vidarbha, and chapters in Hyderabad and Bengaluru. At its heart is the belief that professional excellence is built through continuous learning and meaningful relationships.

Taxmann
50 Items

Specific References